How to Start a Fintech Company After Canadian MSB Registration
November 2, 2026


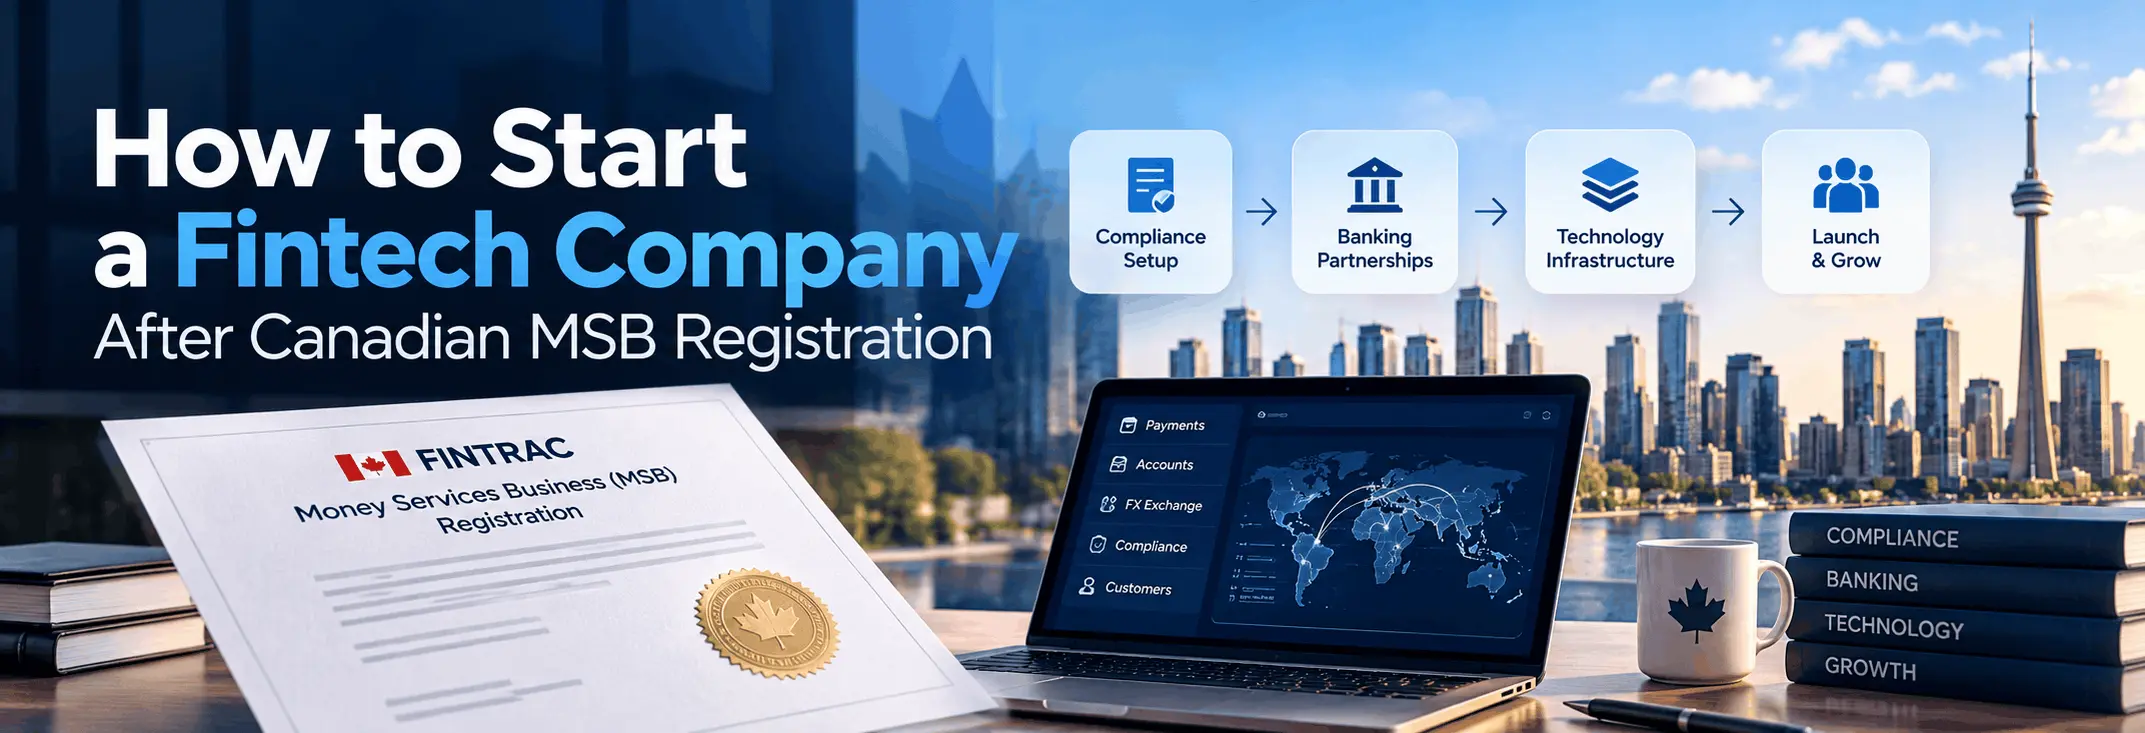
CANADIAN MSB · FINTECH LAUNCH GUIDE · OCTOBER 2026
Canadian MSB registration is a milestone, not a ready-to-launch fintech business. The next steps involve regulatory assessment, banking and payment partners, compliance operations, reliable software, and a sustainable business model.In a conversation with FinHost CEO & Co-founder Platon Mykhalchuk, XlentPay CEO Joao Monteiro discusses the day-to-day realities of operating a payments business. This guide combines those first-hand insights with official Canadian regulatory guidance and payment-market data.
What Does Canadian MSB Registration Actually Allow You to Do?
Money services businesses (MSBs) conducting covered activities in Canada generally must register with the Financial Transactions and Reports Analysis Centre of Canada (FINTRAC). These activities can include foreign exchange dealing, remitting or transmitting funds, and dealing in virtual currency, depending on the services provided.
FINTRAC registration is not a banking licence, an endorsement of your business, or permission to undertake every kind of payment activity. FINTRAC-registered businesses must also meet applicable ongoing AML/ATF requirements. Registration renewal is generally required every two years. See FINTRAC’s MSB guidance.
FINTRAC Registration vs. Bank of Canada PSP Registration
Depending on the activities performed, a business may also be a payment service provider (PSP) subject to the Retail Payment Activities Act (RPAA). The Bank of Canada administers a separate supervisory framework for in-scope retail payment activities. New applicants subject to the framework generally must register before performing those activities. Applicability, exclusions, and timing require a business-specific assessment.
| Area | Purpose | What it does not provide |
|---|---|---|
| FINTRAC MSB registration | Registration and AML/ATF obligations for covered activities | Banking access or a banking licence |
| Bank of Canada PSP registration | Oversight of in-scope retail payment activities | Automatic access to payment networks |
| Banking and provider agreements | Commercial access to services and payment infrastructure | Substitution for regulatory compliance |
Consult the Bank of Canada’s retail payments supervision guidance before deciding which activities can go live.
Canadian Payments Market: Scale, Trends and Opportunity
The Canadian payments ecosystem is large, but overall payment value is not the same as the addressable market for a new MSB. Market data is most useful when paired with a specific customer segment, payment corridor, and differentiated service.
Source: Payments Canada, Canadian Payment Methods and Trends, 2026. Survey measures refer to the surveyed populations, not all Canadian businesses.
Retail Payment Value: 2024 vs. 2025
+5.7% year-over-year payment value growth. Source: Payments Canada (2025–2026 reports).
Where New MSBs May Find Demand
Potential opportunities include cross-border B2B payments, multi-currency wallets, transparent FX, industry-specific payment workflows, and compliant fiat-to-crypto services where permitted. These are hypotheses to validate through market research, not guaranteed growth segments.
Before selecting a product, estimate the target customer base, transaction frequency, average transaction size, corridor economics, and provider acceptance criteria.
Seven Steps to Launch a Fintech Business After MSB Registration
Define Your Business Model and Target Customers
Decide whether you will serve consumers, SMEs, corporates, or specialized industries. Document target jurisdictions, currencies, payment types, expected volumes, pricing, and customer risk profiles. Your product scope determines which regulatory assessments and partners you need.
Deliverable: product and customer scope, projected volumes, and a corridor-level business model.
Operationalize Your Compliance Program
Implement written policies, appoint a compliance officer, assess risks, train staff, and periodically review program effectiveness. Configure appropriate identity checks, recordkeeping, monitoring, reporting, and escalation processes. A technology tool can support these duties but does not replace them.
Deliverable: tested compliance workflows, documented responsibilities, and an escalation process. Review FINTRAC compliance program guidance.
Secure Banking and Payment Partners
Identify partners that support your target customers, industries, currencies, and corridors. Assess onboarding requirements, transaction limits, payment rails, API coverage, settlement, fees, rejected-payment handling, and operational support. Partner acceptance is separate from MSB registration.
Deliverable: documented provider agreements and a realistic map of supported payment flows.
Choose Wallet and Core Banking Technology
Evaluate internal development against a white-label MSB software platform. Consider ledger integrity, auditability, permissions, API connectivity, security, provider dependencies, customization, and maintenance costs.
Deliverable: approved architecture and implementation plan.
Integrate KYC, KYB, AML and Transaction Monitoring
Connect customer onboarding, verification, screening, compliance review, transaction monitoring, and case management to the operating platform. Decide which controls are automated and which require human review. Validate that workflows match your legal and partner obligations.
Deliverable: end-to-end tested onboarding and compliance journeys.
Test Payments, Reconciliation and Customer Support
Run end-to-end tests for incoming and outgoing transfers, fees, balances, FX, payment returns, failed API calls, reconciliation exceptions, and customer complaints. Test provider outages and manual fallbacks where relevant.
Deliverable: documented test results, operational runbooks, and incident ownership.
Launch Carefully, Measure and Scale
Begin with a controlled rollout. Monitor onboarding conversion, payment success rates, processing time, compliance review time, reconciliation exceptions, revenue per customer, and contribution margin. Expand corridors and services only after the operating model is stable.
Deliverable: launch dashboard, incident review cadence, and a data-driven growth plan.
FOUNDER PERSPECTIVE · XLENTPAY × FINHOST
What XlentPay’s Founder Says About Running a Fintech Business
In an interview hosted by Platon Mykhalchuk, CEO & Co-founder of FinHost, Joao Monteiro, CEO of XlentPay, explains the operational realities behind a payments business. The points below summarize the interview excerpts rather than presenting invented direct quotations.
Watch the full interview on YouTube
Compliance, technology, banking agreements, and customer support determine whether a registered business can actually serve clients.
Joao identifies compliance as a leading day-to-day concern, especially when monitoring risky or suspicious activity.
XlentPay’s wallet experience depends on underlying licensed banking institutions for transaction execution. Both API connectivity and compliance alignment matter.
Joao prefers established technology partners to avoid devoting early business resources to building and debugging an entire platform.
Embed the dedicated Shorts video here when its published YouTube URL is available. The full interview above is already embedded.
How Do MSBs Make Money?
Joao describes three primary revenue sources at XlentPay: transaction fees, account-related fees, and currency exchange. He notes that FX, including fiat-to-crypto and crypto-to-fiat conversion, has been particularly important for XlentPay. This is a company-specific insight, not a universal industry revenue distribution.
Transaction fees
Fees for incoming or outgoing transfers, subject to the pricing model and processing costs.
Account fees
Corporate setup charges, monthly subscriptions, or other account-related service fees.
FX and conversion
Conversion charges or spreads, less liquidity, execution, provider, and operational costs.
Illustrative Unit Economics: Revenue Is Not Profit
Illustration only: CAD 5,000,000 × 0.003 = CAD 15,000. It excludes payment provider fees, FX costs, compliance, staff, software, customer acquisition, and other expenses. It is not an estimate of XlentPay or FinHost customer performance.
A useful model estimates contribution margin per transaction and monthly fixed operating costs, not only gross transaction volume. A viable fintech business must support its operational and compliance costs with realistic customer demand.
Build vs. Buy: Selecting Fintech Infrastructure
Building internally offers control over architecture, but requires substantial engineering, testing, security, and maintenance resources. White-label infrastructure may reduce development effort and time to market, but still requires configuration, integration testing, vendor oversight, and regulatory readiness.
| Consideration | Internal development | White-label platform |
|---|---|---|
| Engineering investment | Usually substantial upfront | Often lower initial development effort |
| Customization | Direct architectural control | Depends on platform and contract |
| Integrations | Build or procure separately | Existing integrations may be available |
| Maintenance | Primarily internal | Responsibilities allocated by agreement |
| Regulatory obligations | Remain with the business | Remain with the business |
How FinHost Supports Canadian MSB Technology Launches
FinHost provides white-label core banking and payment infrastructure for MSBs, payment institutions, and EMIs. Depending on the agreed scope and available providers, its platform can support digital wallets, multi-currency account experiences, payment integrations, KYC/KYB workflows, FX capabilities, and back-office operations.
FinHost supplies technology; a customer must still satisfy applicable regulatory obligations, banking approvals, and operational requirements. Explore Canadian MSB software, core banking software options, and FinHost’s platform.
Canadian MSB Launch Readiness Checklist
Use this as a planning aid before accepting live customer transactions. It does not replace a regulatory or legal review.
Frequently Asked Questions
Can I start operating immediately after FINTRAC MSB registration?
Not necessarily. Additional regulatory requirements, banking approvals, and operational controls may apply. A business conducting in-scope retail payment activities may also need Bank of Canada PSP registration.
Do Canadian MSBs need banking partners?
Many MSB models rely on banks or other authorized providers for accounts, settlement, and access to payment rails. Exact arrangements depend on the product and money flows.
Does an MSB need separate PSP registration in Canada?
Possibly. Businesses carrying out retail payment activities covered by the RPAA must assess whether Bank of Canada registration applies, including any relevant exclusions.
Can a Canadian MSB offer crypto services?
Some virtual currency activities fall under FINTRAC’s MSB framework, but additional federal, provincial, securities, or other obligations may apply depending on the service.
How long does an MSB platform launch take?
There is no universal timeline. Banking onboarding, regulatory assessment, compliance implementation, integration scope, and testing often determine readiness.
Can I use white-label software for my MSB?
Yes. White-label technology can support wallets, payments, account management, and back-office workflows, but it does not replace registration, compliance, or banking arrangements.
From MSB Registration to a Working Fintech Business
Canadian MSB registration is a starting point. A sustainable fintech operation also requires appropriate authorizations, compliant processes, reliable banking partners, tested technology, customer support, and disciplined unit economics. XlentPay’s founder illustrates why those pieces must work together.
FINHOST · WHITE-LABEL FINTECH INFRASTRUCTURE
Ready to Plan Your MSB Technology Launch?
Explore the infrastructure needed to build digital wallets, connect payment providers, and manage fintech operations under your brand.
Sources and Further Reading
- FINTRAC: Money services businesses
- FINTRAC: Compliance program requirements
- Bank of Canada: Retail payments supervision
- Payments Canada: Canadian Payment Methods and Trends, 2026
- FinHost × XlentPay: Full founder interview
Regulatory information is general and current to October 2026. It is not legal advice. Requirements depend on the services offered, jurisdictions involved, and applicable exemptions. Seek qualified Canadian legal and compliance advice before launching regulated activities.